Europe's one-day settlement starts in October 2027. The first change lands on 7 December and it falls on whoever is furthest from Brussels.
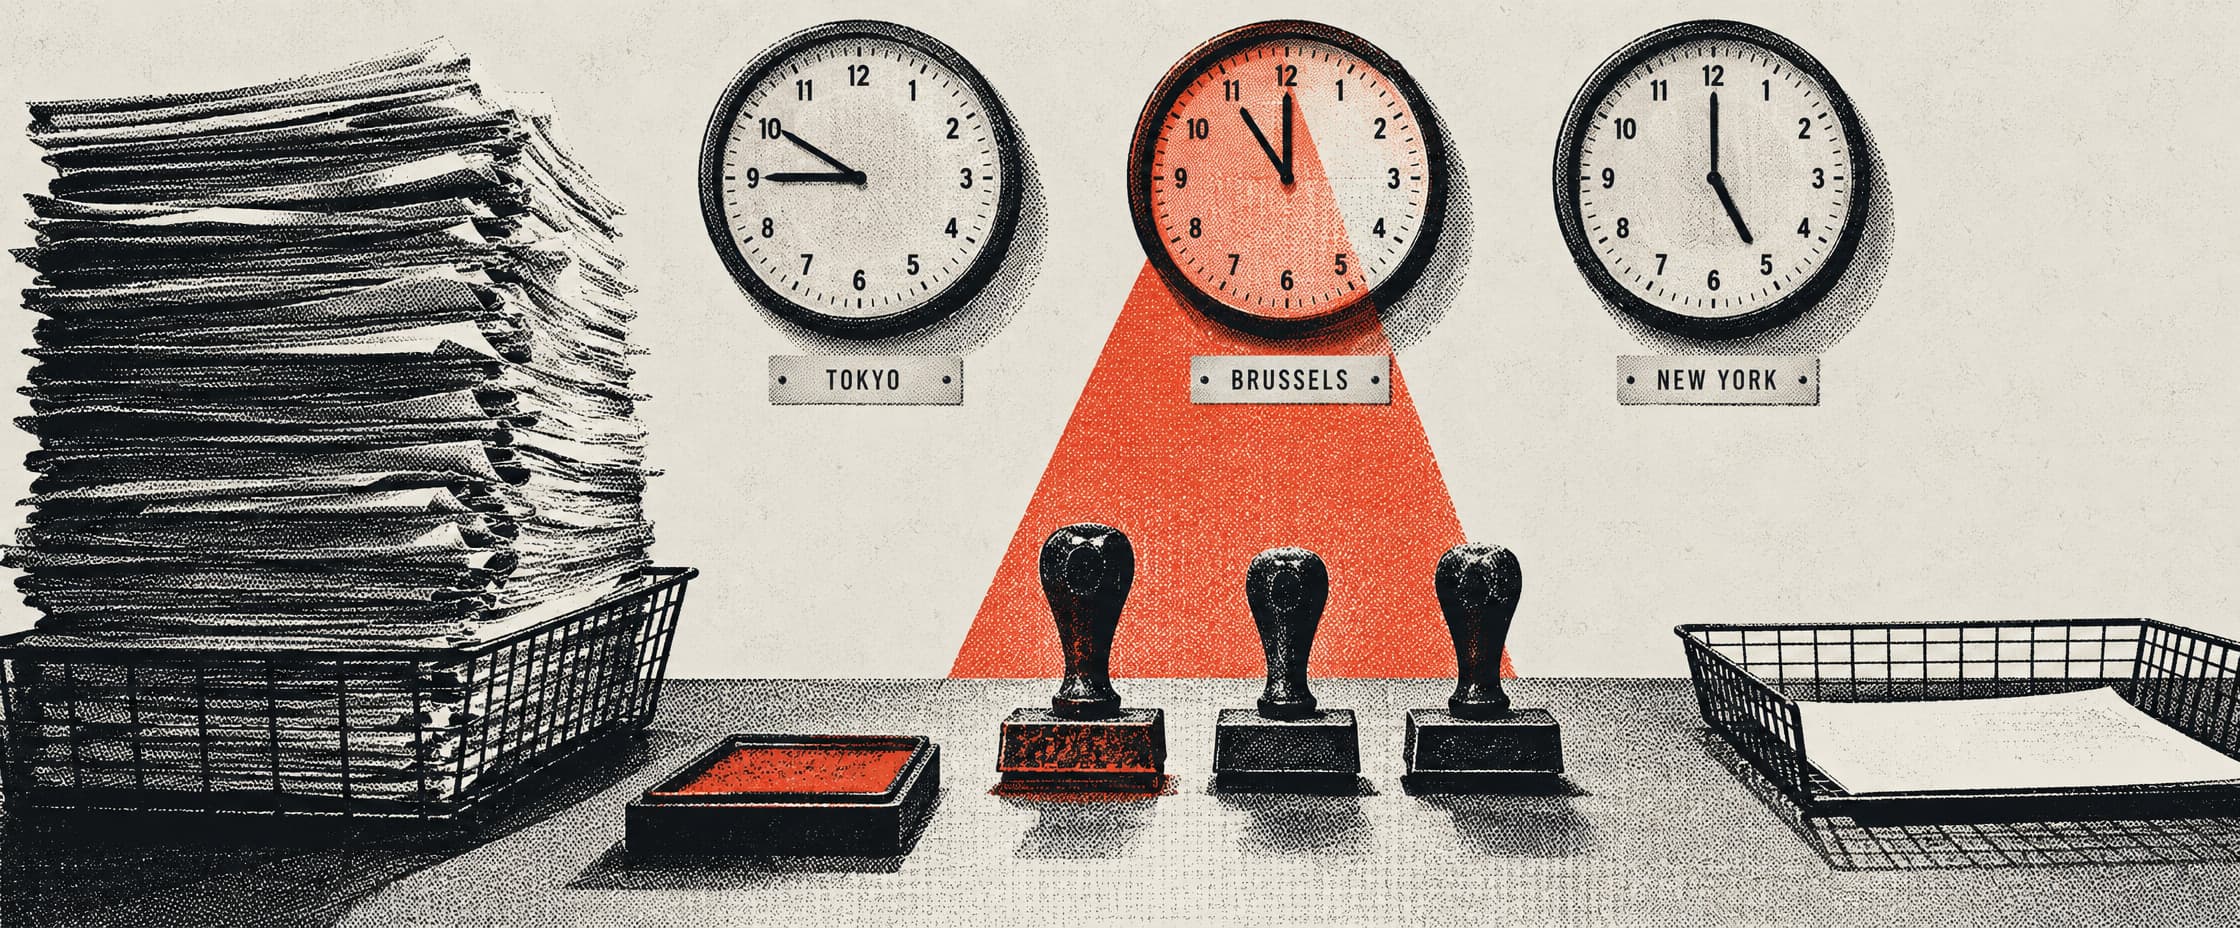
The amended settlement discipline standards replace two allocation deadlines with one, 23:00 CET on the day of the trade. For a client in the same time zone that is a relaxation. For one in Tokyo it is thirteen hours.
Draft, not yet edited. Written by Tomasz Wierzbicki, and not yet through the desk: nothing here has been checked against the sources listed at the foot of the page. Do not act on it.
A Tokyo fund that buys European shares today has until noon tomorrow, Brussels time, to tell its broker where to put them. From 7 December 2026 it has until eleven tonight.
That is the first operative change in the European Union's move to a one-day settlement cycle, and it arrives ten months before the cycle itself. The Commission adopted the instrument on 6 July 2026, as C(2026) 4640 final, amending the regulatory technical standards on settlement discipline in Delegated Regulation (EU) 2018/1229. The Parliament and the Council have until 6 October to object, on ESMA's own reckoning, with publication in the Official Journal expected at the start of the fourth quarter. Scrutiny of a delegated act is a veto or nothing; neither institution can redraft an hour it dislikes.
The carve-out that is not in the new text
The rule being replaced has two limbs, and almost everything interesting is in the second one. Under the current Article 2(2), a professional client must get its written allocation and confirmation to the investment firm by close of business on the day of the trade where it sits in the same time zone as the firm, or where the order was executed before 16.00 CET. Where the client's time zone differs by more than two hours, or the order was executed after 16.00 CET, it has until 12.00 CET on the following business day.
The replacement is one sentence with one hour in it. The client must ensure the firm receives the allocation and the confirmation as soon as possible and by no later than 23:00 CET on the business day on which the transaction took place. Retail clients get the same hour, under the replaced Article 3.
Read the two limbs against the new single deadline and the direction of travel is not uniform. For a Frankfurt client whose close of business is 18:00, 23:00 CET is five hours of relief. For a client in Tokyo, noon tomorrow becomes eleven tonight, which is thirteen hours earlier, and the arithmetic of what that means is worth doing rather than gesturing at. In December, 23:00 in Brussels is 17:00 in New York, 06:00 the following morning in Singapore and 07:00 in Tokyo. An Asian institution trading European equities already works the European afternoon; from December it must also finish its allocations before it sleeps, because the deadline falls before its own next business day starts. The two-hour concession existed because somebody once thought about this. It is not in the new text.
The text also says CET and says nothing about central European summer time. That is not new — the current provision says CET too — and it is also not answered anywhere this desk could find.
Three dates, and ESMA names two
Article 2 of the adopted act sets out its own timing, and it sets out three dates, not one. The general application date is 7 December 2026. A second tranche applies from 1 July 2027: the place-of-trading field in settlement instructions, the amendments to the fail-monitoring system in Article 13, the participant duty to report the main reasons for fails monthly, the rewritten reporting article, and the amended reporting annexes. Everything else — the CSD-side instruction timing, hold and release, auto partial settlement, three settlement batches or real-time gross settlement, automated collateralisation — applies from 11 October 2027, the day the cycle halves.
ESMA's statement of 20 July names a "first deadline" and a "final deadline" and does not mention the middle one. It is easy to see why: the July tranche is the measurement apparatus, and measurement apparatus is nobody's programme milestone. It is also the part that determines whether anyone can say afterwards what happened. The reporting that shows how the market settles under the new regime switches on fourteen weeks before the regime changes, which is the baseline a supervisor will be comparing against for years.
One deadline is hard and the other is not
Put the two instruction deadlines side by side, because they were not drafted by people with the same problem.
The client's deadline, from December: the firm must receive the allocation "by no later than" 23:00 CET on the trade date.
The CSD participant's deadline, from October 2027, in the new Article 5(5): CSDs "shall require participants to send settlement instructions as soon as possible and where feasible by 23:59 CET" on the trade date. Recital 7 then removes any doubt about what happens if they do not. A later instruction does not stop the CSD processing it, and it does not give rise to cash penalties, which apply only on the conditions in Article 7(2) of the CSDR.
So the buy-side hour is an obligation and the sell-side hour is an aspiration, and the aspiration arrives ten months after the obligation. Neither of those is an accident. The client's allocation is the input everything downstream waits for, and the drafters have made the first link in the chain the only one with a firm time on it.
How that obligation is collected is the other half. The amended Article 2(1) requires the investment firm to ensure, through contractual arrangements, that the client confirms in writing, in an electronic standardised format, using the international open communication procedures and standards the CSDR defines. Unstructured communication survives only for temporary technical unavailability or service disruption, duly documented. A deadline written in a Commission regulation is therefore enforced, in practice, by a clause in a client agreement with a party the EU does not supervise. The firm that has not repapered its professional client base by 7 December is the one its national authority will ask about it.
The shock absorbers are on the last date
The functionality that exists to stop a missed hour becoming a fail is all in the October 2027 tranche. Auto partial settlement, which lets a delivery of eighty per cent of a line settle rather than fail whole. Partial release of a held instruction. Automated collateralisation for intra-day credit. Three settlement batches a day, or real-time gross settlement, or both.
One deletion deserves naming. Article 12 currently carries a derogation that lets a CSD skip hold and release and partial settlement altogether if its settlement fails stay below EUR 2,5 billion a year and its fail rate below 0,5 %. The adopted act replaces Article 12 with the collateralisation duty. The derogation does not reappear anywhere else in the text.
Between December 2026 and October 2027 the settlement cycle is still T+2, so the compressed front end runs with a day of slack behind it. The charitable reading is a dress rehearsal with a margin, and it is probably the right one. The other reading is that a margin is exactly what makes a front end look fine for ten months.
What failing costs, and why nobody raised it
When a trade does fail, the failing participant pays a daily cash penalty to the receiving one. The rates come from Delegated Regulation (EU) 2017/389, set on 11 November 2016 and unchanged since. ESMA advised on 19 November 2024 that the design should stay and the rates should rise moderately across most asset classes, and said plainly why it was not recommending more: a significant increase could divert resources from the investment the move to T+1 requires. Searches of EUR-Lex and the Commission's register on 25 September 2026 returned no act amending 2017/389. We could not establish that one exists.
That is a defensible position and it is also the sentence to keep. The price of failing to settle was held where it was so that firms could afford to stop failing.
ESMA's final guidelines on allocations and confirmations are expected in October 2026, from a consultation that closed on 7 July, and are expected to apply on 7 December. Guidance on how to read the obligation, roughly six weeks before it binds, for a change that has to be agreed in writing with clients in every time zone a firm trades from. Every firm can tell you the deadline. None of them has had to say how many of those clients have signed.
Written from
Primary The document itself. Claims in this piece rest only on these.
- Regulation (EU) 2025/2075 amending Regulation (EU) No 909/2014 as regards a shorter settlement cycle in the UnionOpened for this piece via the Publications Office's own copy. Read: the replacement wording of Article 5(2) of Regulation (EU) No 909/2014, the carve-outs (privately negotiated transactions executed on a venue, bilaterally executed transactions reported to a venue, initial book-entry recording, and securities financing transactions documented as a single transaction with two linked operations), the amendments to Articles 74 and 75, recitals 2, 3 and 6, and the application date of 11 October 2027. Source for the date of the cutover and for the fact that the settlement period is set by the level 1 regulation and nothing else. It sets no operational deadline of any kind; every hour printed in this piece comes from the delegated act below.
- Commission Delegated Regulation amending the RTS laid down in Delegated Regulation (EU) 2018/1229 on settlement discipline, C(2026) 4640 finalThe adopted act, downloaded from the Commission's own register and read: the explanatory memorandum's article-by-article description of points (1) to (13), recitals 1 to 9, the full enacting text of Article 1 points (1) to (13), and Article 2 on entry into force and application. Source for: the 23:00 CET allocation and confirmation deadline in the replacement Article 2(2) and the identical deadline for retail clients in the replacement Article 3; the requirement for an electronic, machine-readable format and for international open communication procedures and standards; the two-hour acknowledgement; the new Article 5(5) wording, including 'where feasible by 23:59 CET'; the replacement of Article 10 with auto partial settlement; the replacement of Article 12 with the automated collateralisation duty; the Article 11(4) wording on RTGS or three batches; the amendments to Articles 8, 13, 14 and 23; and the three application dates in Article 2, 7 December 2026, 1 July 2027 and 11 October 2027, with the point numbers attached to each. Recital 7 is the source for the statement that late settlement instructions neither stop a CSD processing them nor give rise to cash penalties. The two annexes to the act, which carry the amended reporting tables, were not read field by field, and no claim here rests on them. At the time of writing the act had not appeared in the Official Journal; the text read is the adopted version, which the scrutiny period can still stop but not alter.
- Commission Delegated Regulation (EU) 2018/1229, RTS on settlement discipline, as currently in forceConsulted for the text being amended. Read Articles 2, 3, 10, 11 and 12. Source for the current two-limb deadline in Article 2(2), close of business on the trade date where the client is in the same time zone or the order was executed before 16.00 CET, and 12.00 CET on the following business day where the time zones differ by more than two hours or the order was executed after 16.00 CET; for the current retail deadline of 12.00 CET on the following business day; for the current Article 10 duty to allow partial settlement; for the current Article 11(4); and for the Article 12 derogation and its two thresholds, EUR 2,5 billion of fails a year and a 0,5 % fail rate. Only the operative words are quoted. The rest of the regulation, including the buy-in provisions and the annexes, was not read for this piece.
- Statement on T+1 preparations, ESMA74-2119945926-3773Read in full. Source for ESMA's own framing of a 'first deadline' of 7 December 2026 and a 'final deadline' of 11 October 2027, and for the list of what sits on the second of those, instructions sent early enough, auto-partial settlement, hold and release, auto-collateralisation. Source for ESMA's summary of the first and second readiness surveys, an increasing level of awareness and commitment alongside uneven implementation across markets, sectors and firms; the underlying survey data were not supplied and this desk has not seen them. Source for the warning that a persistent inability to meet T+1 deadlines could reduce counterparties' willingness to trade, and for the statement that the level 3 guidance was in the last stages of review. The statement names two deadlines and does not mention 1 July 2027; the observation that a third date exists is this desk's reading of Article 2 of the adopted delegated act, not a correction ESMA has published.
- EU T+1: related legislative and regulatory developmentsESMA's own status tracker, opened for this piece. Source for the scrutiny period running until 6 October 2026 for non-objection by the Parliament and the Council, for publication in the Official Journal and entry into force expected at the beginning of Q4 2026, and for the phased application from 7 December 2026. The tracker does not mention cash penalties or Delegated Regulation (EU) 2017/389.
- ESMA consults on revised guidelines to support smoother allocations and confirmations under T+1Press release read. Source for the consultation running from 26 May to 7 July 2026, for final guidelines expected in October 2026, for an expected application date of 7 December 2026, and for the removal of references to non-electronic methods such as oral allocations except during temporary technical disruption. The consultation paper itself and the responses to it were not read.
- ESMA finalises its advice on the CSDR penalty mechanismThe press release announcing the technical advice was read; the final report behind it, ESMA74-2119945925-2059, was not opened. Source for the date of the advice, for its recommendation to keep the design of the penalty mechanism and apply an overall moderate increase in rates across most asset classes, and for ESMA's stated reason for not going further, that a significant increase could divert resources from the investment the move to T+1 requires. Nothing here rests on any individual rate.
- Commission Delegated Regulation (EU) 2017/389 on the parameters for the calculation of cash penalties for settlement failsAttempted four times and not read. The EUR-Lex HTML returned empty and the PDF's text layer would not decode into legible characters on this desk. No penalty rate is printed in this piece for that reason. Searches of EUR-Lex and of the Commission's register on 25 September 2026 returned no act amending this regulation, and the body says only that we could not establish one, not that none exists.
- ESMA Final Report on amendments to the RTS on settlement discipline, ESMA74-2119945926-3430Not read. The PDF would not yield usable text on this desk. It is the draft the Commission adopted, and the body relies on the adopted act instead, which is the instrument that will bind. ESMA's impact assessment and its cost-benefit analysis, which sit in the annexes to this report, were therefore not read, and this piece prints no cost figure of any kind.
Reporting Attributed, not relied on. Where the reporting is the fact, it says so.
- EU T+1 Industry Committee, guides and resourcesThe committee's published resource index was opened. It lists a high-level roadmap, a settlement handbook whose second iteration is dated June 2026, a testing plan whose second version is dated September 2026, and gating event guidance dated June 2026. It dates the roadmap to November 2025; the Commission's own footnote in C(2026) 4640 dates it to 30 June 2025. This desk did not resolve that discrepancy and prints no roadmap date. None of the committee's documents is law and nothing in the body rests on them.
- Note on the two CSDR delegated regulations adopted in July 2026Read to check whether a second act adopted the same week touched cash penalties. It does not: the second act is C(2026) 4642, amending Delegated Regulation (EU) 2017/392 on what a CSD gives its competent authority for the Article 22(1) review. Nothing in the body rests on this note.
Related
Six rules for building software with an AI assistant, in use at a Belgian insurer. The security sits inside each rule, which is the good idea and the expensive part.
DAHNIN treats the model as a fast, confident junior with no memory, and gives it written context, hard limits and two reviews. Four of its citations check out. One of them does not cover what it is cited for, and the rule that reads most like a control is not one.
The High Table can ban the friend who invited me. That one rule does more work than any moderator could.
I joined expecting a scam, stood near Trinity Square at midnight, and came away impressed and uneasy in roughly equal measure. The company that publishes this page owns the game, which is why you should read the second half.
Four clocks, one incident. At a financial entity two of them are not running, and the fastest starts when somebody decides.
DORA's first report is due four hours after an incident is classified as major and never later than a day after anyone knew. The GDPR's seventy-two hours start from a different moment, and the person who owns that moment is usually in another meeting.